Why a $50k Prop Firm Account Isn’t Really a $50,000 Account
Prop firms advertise account sizes of $50,000, $100,000 and even $150,000, but those numbers often tell traders very little about how much risk they actually have.
Published
Prop firms love big numbers.
$25K accounts. $50K accounts. $100K accounts. $150K accounts.
Those numbers dominate pricing pages and promotional material across the prop trading industry. They also make it easy for traders to compare products at a glance.
The problem is that account size often tells traders surprisingly little about how much risk they actually have.
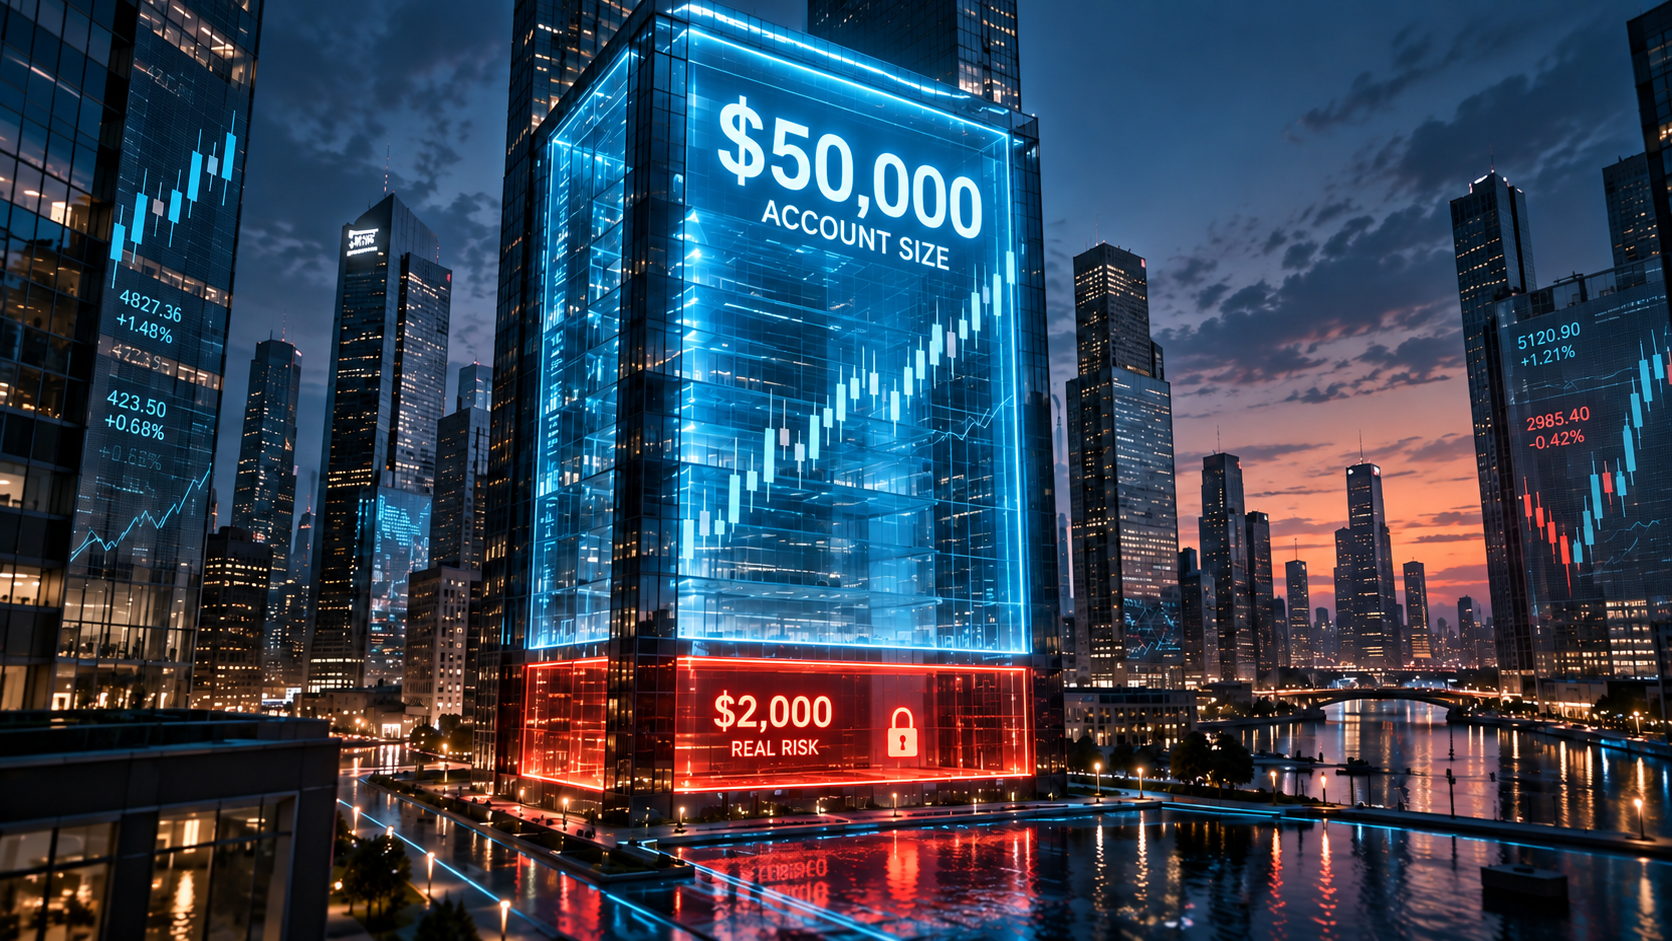
A trader purchasing a $50,000 prop firm evaluation generally does not have $50,000 available to lose. In many cases, the account will be closed after losses of around $2,000.
NQ1! Market Snapshot
Reported Market State
Auction Activity
Rejecting Lower Prices
Market context
As of Sep 25, 3:00 PM CDTPrice is inside the current value area and above RTH VWAP.
- Nearest mapped level: OR15 High (30,890.00), 1.50 points below price.
- Price is above the prior value area.
- Reported auction activity: Rejecting Lower Prices.
- New York session range: 9.34 ATR. Net displacement: +2.53 ATR.
Market location
- Current value
- Inside
- Prior value
- Above
- RTH VWAP
- Above
- Prior RTH VWAP
- Above
Nearby levels
- OR15 High30,890.00
near · 1.50 pts · 0.05 ATR · Price above
- VWAP +1 SD30,905.48
extended · 13.98 pts · 0.49 ATR · Price below
- Asia High30,906.00
extended · 14.50 pts · 0.51 ATR · Price below
- Point of Control30,914.00
extended · 22.50 pts · 0.79 ATR · Price below
Level clusters
VWAP +1 SD / Asia High
30,905.48–30,906.00
Midpoint 14.24 pts from price · 0.50 ATR to midpoint
ATR Upper / Value Area High
30,931.17–30,932.00
Midpoint 40.09 pts from price · 1.40 ATR to midpoint
RTH High / Previous 4H High
30,951.50–30,951.50
Midpoint 60.00 pts from price · 2.09 ATR to midpoint
FAILED LOWER
For traders trying to understand what they are actually buying, that $2,000 may be far more important than the $50,000 printed at the top of the account.
The Account Size Is a Product Tier
Consider Apex Trader Funding's current $50,000 Intraday Evaluation.
The account starts at $50,000 and carries a $3,000 profit target. But its maximum intraday trailing drawdown is $2,000.
The initial failure threshold is therefore $48,000.
Viewed through the marketing number, the trader has purchased a $50,000 account.
Viewed through risk, the trader has approximately $2,000 of room to be wrong while attempting to make $3,000.
Topstep illustrates the same distinction.
Its current Maximum Loss Limits are $2,000 on a $50,000 Trading Combine, $3,000 on a $100,000 account and $4,500 on a $150,000 account.
So while the advertised account balance triples from $50,000 to $150,000, the maximum loss allowance increases from $2,000 to $4,500.
For a trader managing risk, those are arguably the numbers that deserve more attention.
The headline account balance is better understood as a product tier than a literal representation of capital available to lose.
A $2,000 Drawdown Isn't Always a $2,000 Drawdown
Even maximum loss figures do not tell the entire story.
How the drawdown is calculated can dramatically change the experience of trading the account.
Apex's intraday trailing drawdown follows the account's highest equity in real time, including unrealized gains.
Suppose a trader begins with a $50,000 account and a $2,000 trailing threshold.
The initial threshold is $48,000.
The trader enters a position and the account reaches $50,900 in unrealized equity. The threshold can then move higher with that new equity peak.
If the trade subsequently reverses, that threshold does not move back down.
The trader may give back unrealized profit without taking a large realized loss, yet still lose some of the account's available risk cushion.
Compare that with an end-of-day trailing drawdown.
Apex also offers EOD accounts where the threshold moves based on the highest end-of-day balance rather than intraday equity highs. A $50,000 account with a $2,000 drawdown still begins with the same $48,000 threshold, but profitable trades during the session do not move that threshold simply because they were temporarily ahead.
Same $50,000 headline.
Same $2,000 drawdown.
Very different trading environment.
That is why traders comparing prop accounts need to understand not only how much they can lose, but how the firm measures that loss.
Position Size Changes the Equation Again
Contract limits add another layer.
Topstep currently allows up to five standard contracts in its $50,000 Trading Combine, 10 on the $100,000 account and 15 on the $150,000 account.
Those limits increase substantially with the advertised account size.
The loss allowance does not scale at the same rate.
A trader who sees "$150,000 account" and "15 contracts" without also noticing the $4,500 Maximum Loss Limit may form a very different impression of the account's actual risk capacity.
The important relationship is not simply account size versus contract limit.
It is contract exposure versus allowable loss.
That is the combination that determines how quickly an account can disappear.
Passing the Evaluation Doesn't End the Math
Funded-level accounts introduce another set of numbers traders need to understand.
Apex's current $50,000 Intraday Performance Account, for example, carries a $2,000 maximum trailing drawdown.
But receiving a payout requires more than simply becoming profitable.
For the $50,000 account, Apex currently requires five qualifying trading days with at least $200 of profit on each qualifying day, a $52,100 safety-net balance and a minimum balance of $52,600 before a payout request can be made. A consistency requirement also applies.
The account may still be labeled $50,000.
But the numbers that matter to the trader now include:
$2,000 of allowable drawdown.
$2,100 of safety-net profit.
A $52,600 minimum payout balance.
Five qualifying trading days.
And a consistency requirement.
The marketing number hasn't changed.
The economic reality of the account has.
Topstep's Express Funded Account provides another example.
Its payout structure also ties eligibility to qualifying trading days and account-specific loss rules. After a payout, the risk structure can change again depending on the account's Maximum Loss Limit.
That post-payout behavior matters enormously.
A trader evaluating a prop account should therefore be asking not only what happens before the first payout, but what the risk structure looks like after money is withdrawn.
Stop Comparing $50K to $50K
This is where many prop firm comparisons go wrong.
Traders naturally compare a $50,000 account at Firm A with a $50,000 account at Firm B.
But those products may have completely different:
- drawdown amounts,
- drawdown calculation methods,
- contract limits,
- daily loss limits,
- payout thresholds,
- consistency requirements,
- withdrawal caps,
- and post-payout risk rules.
The shared "$50,000" label can create the illusion that the accounts are comparable when their actual trading conditions are not.
A more useful comparison starts by temporarily ignoring the headline account size.
Instead, ask:
How much can I actually lose before the account is closed?
Then ask:
What causes that loss threshold to move?
Those two questions alone will reveal more about many prop accounts than the advertised balance ever will.
A Better Way to Compare Prop Firm Accounts
Traders evaluating prop firms may be better served by comparing a smaller set of numbers:
Maximum loss allowance: How much can actually be lost before failure?
Drawdown type: Is it static, end-of-day trailing or intraday trailing?
Unrealized profit treatment: Can an open winning trade move the loss threshold higher?
Daily loss limit: Is there a separate restriction on how much can be lost in one session?
Maximum position size: How much leverage can the trader deploy against the available drawdown?
Payout threshold: How much profit must be accumulated before money can be withdrawn?
Consistency requirements: How much can one trading day contribute toward payout eligibility?
Post-payout rules: What happens to the trader's loss cushion after taking money out?
Those are the numbers that define the account traders actually experience.
Why the Big Number Still Exists
None of this means account sizes are useless.
They provide an easy way for firms to organize products and frequently determine pricing, contract limits, profit targets and payout structures.
But traders should understand what the number represents.
A $50,000 prop account is not economically equivalent to depositing $50,000 into a personal brokerage account.
The trader generally cannot lose $50,000.
The trader may not be controlling $50,000 of live firm capital.
And in many modern programs, the trader is operating in a simulated environment governed by a much smaller maximum loss allowance.
That makes "$50,000" less a measurement of usable capital and more a name for the account configuration.
The Number That Actually Matters
Prop firms are unlikely to stop advertising large account balances.
"$150,000 funded account" is easy to understand and far more compelling marketing copy than "$4,500 maximum loss allowance."
But traders do not survive prop accounts based on the number in the account name.
They survive based on the amount of risk they have available and how effectively they protect it.
So the next time two prop firms both advertise a $50,000 account, don't start by asking which $50,000 account is better.
Start with a different question:
How much room does each account actually give me to be wrong?
For a trader trying to survive long enough to receive a payout, that is the number that matters.
Related Firms